Mold After a Short-Paid Dry-Out: Where the Coverage Question Goes

BYSteve Jafari, General ManagerMIAMI-DADE & BROWARD

Florida licenses the people who assess and remediate mold and sets deadlines for giving notice of a claim. Your policy and the facts of your loss set what your insurer owes. Questions about coverage belong with your insurer, your agent, or a licensed public adjuster or attorney.
Call (786) 213-9489Does insurance cover mold after a short-paid dry-out?
Your policy and the facts of your loss set what your insurer owes. Questions about coverage belong with your insurer, your agent, or a licensed public adjuster or attorney. What is not a coverage question is the building science underneath it, and that part is public.
Restoration Doctor is a water mitigation company. Florida law bars a contractor from interpreting policy provisions or advising an insured about coverages or duties under a property insurance policy, so this post does neither. It is general information, not legal advice and not insurance advice. Coverage decisions belong to your carrier.
What this page can do is narrower. It explains from federal guidance why a dry-out that ends early and growth that appears later are connected as moisture.
- Federal guidance puts the drying window at 24 to 48 hours. That window, not a carrier's estimate, is what growth responds to.
- Growth after a water loss is usually behind a finish rather than on it, which is why a visual all-clear is not a moisture all-clear.
- Florida licenses mold assessors and mold remediators separately, and the statute keeps one company from doing both on the same structure in most cases.
- We invoice the property owner. You are responsible for payment under your signed agreement, whether or not your insurer pays.
Why does a dry-out that ends early show up later as mold?
Because moisture is what growth depends on, and it is the part a dry-out is supposed to remove. EPA's guide for homeowners states it plainly: "The key to mold control is moisture control."
The same guide puts a clock on it. It says "It is important to dry water-damaged areas and items within 24-48 hours to prevent mold growth."
It also says that where wet or damp materials are dried inside that window, "in most cases mold will not grow."
A material that is still wet after that window has kept the condition growth depends on. Equipment leaving the property early is one way that happens. So is a supply line that kept weeping behind a cabinet, an air handler that could not hold humidity down while the doors stayed open, and a wall cavity nobody opened. Why a material stayed wet is a question of fact about that building, and it is worth answering rather than assuming.
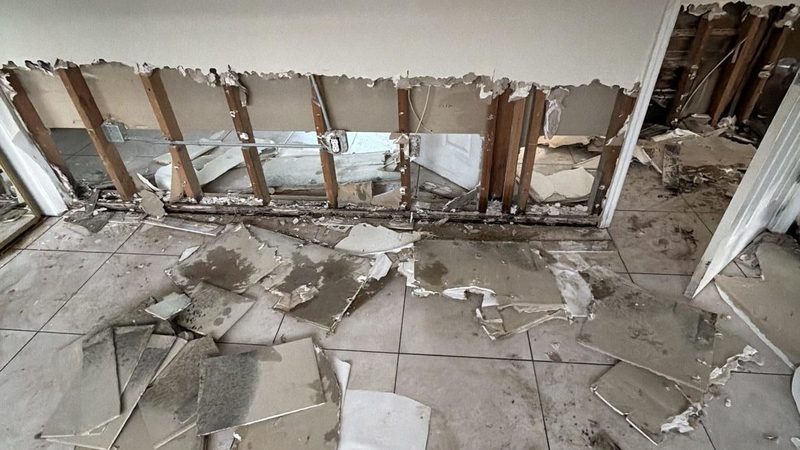
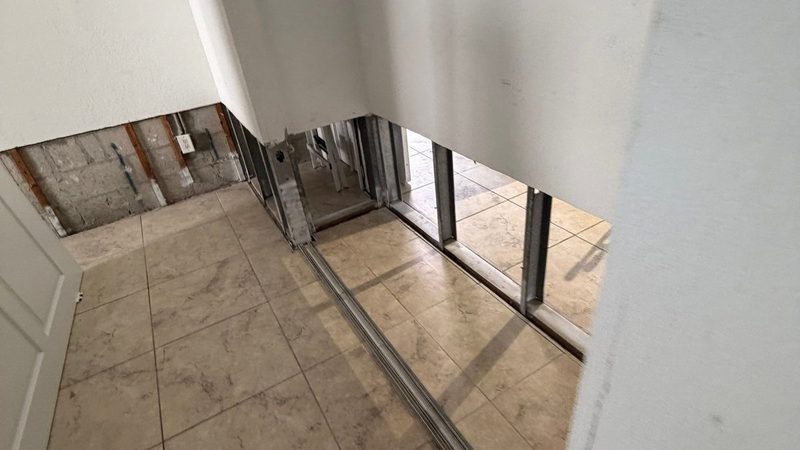
This is also why the growth you can see is rarely the growth that matters. EPA lists the hiding places as "the back side of dry wall, wallpaper, or paneling, the top side of ceiling tiles, the underside of carpets and pads."
Opening those places is not a casual job. The same guide warns that "removal of wallpaper can lead to a massive release of spores if there is mold growing on the underside of the paper."
One more line from EPA reframes what a successful dry-out even means: "It is impossible to get rid of all mold and mold spores indoors; some mold spores will be found floating through the air and in house dust."
Nobody is chasing zero. The target is materials at their drying goal and indoor humidity held down, which EPA puts "below 60 percent (ideally between 30 and 50 percent) relative humidity."

What does Florida law actually say about mold?
The Florida statutes that name mold sit in chapter 468, part XVI, titled Mold-Related Services. Every provision in that part regulates people rather than policies.
Florida licenses who may assess mold and who may remediate it. Your policy and the facts of your loss set what your insurer owes. Questions about coverage belong with your insurer, your agent, or a licensed public adjuster or attorney.
Timing is the one place a statute does bite, and it is worth reading in the original rather than in anyone's summary. Section 627.70132 sets outside dates for notice of a claim. Subsection (2) carries the two quoted below, and it tolls those periods for a named insured deployed to a combat zone. Subsection (4) sets different dates again for loss assessment coverage on a condominium unit owner's policy. How any of it applies to your file is a question for your agent, your carrier, a licensed public adjuster or an attorney, not for a contractor.
- Chapter 468, part XVI defines mold, licenses assessors and remediators, sets their insurance minimums and lists what they may not do.
- Section 627.70132(2) provides that a claim or reopened claim "is barred unless notice of the claim was given to the insurer in accordance with the terms of the policy within 1 year after the date of loss."
- The same subsection provides that a supplemental claim "is barred unless notice of the supplemental claim was given to the insurer in accordance with the terms of the policy within 18 months after the date of loss."
- Subsection (4) sets its own dates for loss assessment coverage under section 627.714, including an outside limit of 3 years after the date of loss.
Where in a policy do the mold terms actually live?
Your declarations page names the policy form and any endorsements attached to it. Your policy and the facts of your loss set what your insurer owes. Questions about coverage belong with your insurer, your agent, or a licensed public adjuster or attorney.
What should you ask your carrier in writing?
Questions about your policy and your claim go to your insurer. Florida bars a contractor from drafting that correspondence or advising an insured on it, under section 489.147(2)(d). Your policy and the facts of your loss set what your insurer owes. Questions about coverage belong with your insurer, your agent, or a licensed public adjuster or attorney.

Who is allowed to assess and remediate mold in Florida?
Florida splits the work in two and licenses each half. Section 468.8411 defines mold as "an organism of the class fungi that causes disintegration of organic matter and produces spores," and both statutory definitions turn on scale.
Mold assessment and mold remediation are each defined by reference to growth "of greater than 10 square feet." Section 468.8414 then requires an applicant for either license to have "documented training in water, mold, and respiratory protection."
The provision most property owners never hear about is the separation rule, and it cuts against the interest of any company that would rather sell you both halves.
Under section 468.8419, a person may not "perform or offer to perform any mold remediation to a structure on which the mold assessor or the mold assessor's company provided a mold assessment within the last 12 months."
What that separation means when a protocol is written is covered in Mold Condition 1, 2 and 3.
The same section carves out a certified contractor classified as a Division I contractor under section 489.105(3), and adds that the department may require such a contractor's remediation contract to disclose "that he or she has the right to request competitive bids."
It also bars an assessor from taking or paying a referral fee to a remediator, and bars an engagement in which "the fee payable for the assessment, is contingent upon the conclusions of the assessment."
Read together, those provisions exist so that the party telling you how bad it is does not profit from the answer being worse. Ask any company you are considering which license it holds, then verify it on the state's license verification portal.
Two more provisions matter when you are signing something. Section 468.8421 sets liability insurance minimums for both roles, at not less than one million dollars, and the remediator's policy must include "specific coverage for mold-related claims."
Section 468.8422 requires a mold contract to be in a signed record. It also states that "a mold assessment contract is not required to provide estimates related to the cost of repair of an assessed property," so ask for a repair number separately and in writing.
What documents should a mitigation contractor hand you?
This is the part a contractor can answer without stepping anywhere near your policy. The documentation is the work product, and you should hold all of it whether or not a claim is ever filed. Restoration Doctor writes scopes in Xactimate, the same line-item format adjusters price from, so the file you receive can be read line by line by whoever reviews it.
What a documentation set should let a stranger reconstruct is simple. Which materials were wet, how wet they were, where the equipment sat, how long it ran, and what the readings looked like on the day drying stopped. If a set cannot answer those questions, a later conversation about mold has nothing to stand on, because EPA's own guidance turns on how long materials stayed wet.
There is one honest limit to state here. We cannot promise what any carrier will pay, on the mitigation portion or on the mold portion. Documentation makes a file legible. It does not make a coverage decision.
- Moisture readings by material and location, with the instrument type noted and dated entries.
- The drying goal set for each affected material, and the readings on the day drying ended.
- An equipment log with placement dates, removal dates and unit counts by room.
- Daily monitoring records, including temperature and relative humidity inside the drying area.
- Photographs of the affected assemblies, including anything opened up during the work.
- A line-item scope in Xactimate format, plus the invoice that matches it.

Who pays the mitigation invoice while the mold question is open?
We invoice the property owner. You are responsible for payment under your signed agreement, whether or not your insurer pays. Pricing and payment terms are set out in your written agreement.
We give you our photos, moisture readings and invoice. They are yours to share with your insurer, or keep. We do not interpret your policy, negotiate with your insurer, or represent you in your claim. Your policy and the facts of your loss set what your insurer owes.
Where can I read the authorities for myself?
Statutes and federal guidance change. Every source below was read in full before this post was written, and you should confirm the current text before relying on any of it.
| Source | Link |
|---|---|
| EPA, A Brief Guide to Mold, Moisture and Your Home — the 24 to 48 hour drying window, hidden mold locations, porous materials and the humidity target | EPA mold guide |
| Florida Statutes chapter 468, part XVI, Mold-Related Services — the full part listing, from definitions through rulemaking authority | Ch. 468, part XVI |
| Fla. Stat. 468.8411, the definitions of mold, mold assessment, mold assessor, mold remediation and mold remediator | Fla. Stat. 468.8411 |
| Fla. Stat. 468.8419, prohibitions and penalties, including the 12-month separation of assessment from remediation and the referral-fee bars | Fla. Stat. 468.8419 |
| Fla. Stat. 468.8421 and 468.8422, the liability insurance minimums and the signed-record contract requirement | Fla. Stat. 468.8421 |
| Fla. Stat. 627.70132, notice of property insurance claim, carrying the one-year and eighteen-month bars | Fla. Stat. 627.70132 |
| Fla. Stat. 489.147, prohibited property insurance practices by contractors, including paragraph (2)(d) | Fla. Stat. 489.147 |
| Fla. Stat. 626.854, the definition of a public adjuster and the prohibitions attached to that role | Fla. Stat. 626.854 |
| Standard Flood Insurance Policy, Dwelling Form, article V.D.4, at 44 C.F.R. part 61, appendix A(1). This is the federal flood form and not a homeowners policy | 44 C.F.R. pt. 61, app. A(1) |
| Florida DBPR licensing portal, where a mold assessor or mold remediator license is verified | Verify a licensee |
| Sister sites in other markets | restorationdoctors.com and restorationdoctordc.com |